Your Next Move
Starts Here
Everything you need to make buying a home feel a whole lot simpler, with local expertise and honest advice every step of the way.
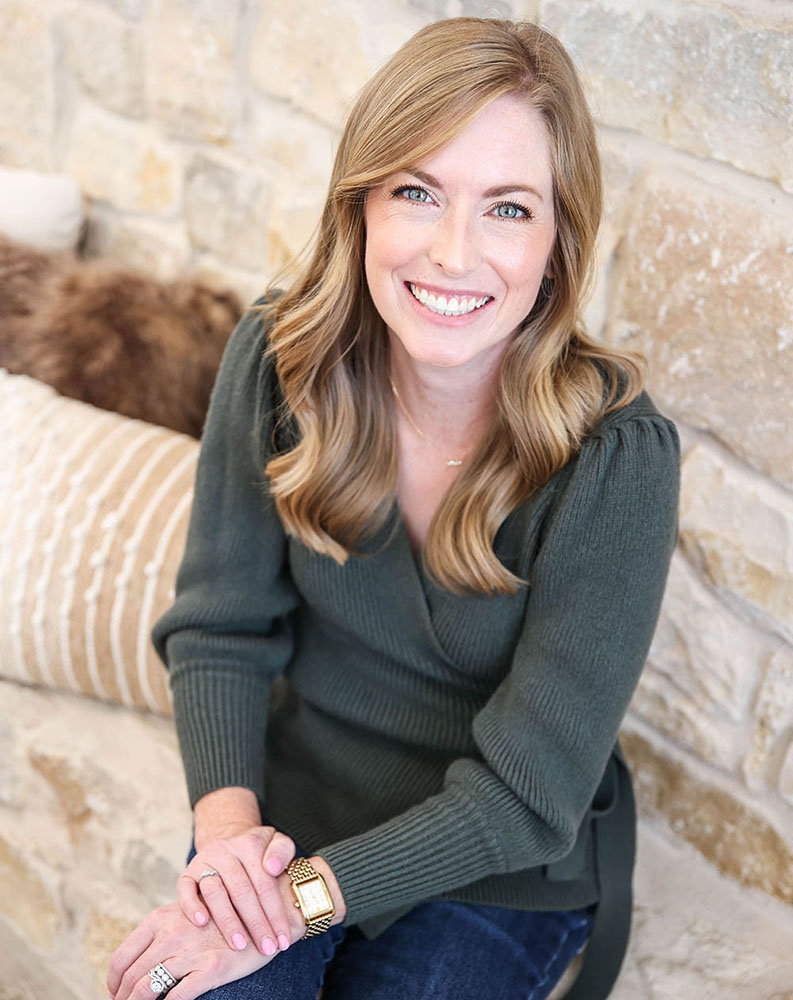
Meet your agent
A guide who's been there
I'm Anna, a West Texas Realtor and investor who has spent the last decade buying, improving, and managing homes of my own. I'll help you look past the listing photos to what really matters — layout, condition, long-term value, and how a home will fit your everyday life — then negotiate with confidence on your behalf.
More About Me →The Buying Process
-
Get Pre-Approved
Know your budget and options
-
Search & Explore
Find homes that fit your goals
-
Make an Offer
I'll guide you through a strong, strategic offer
-
Under Contract
We'll handle the details together
-
Closing Day
Get the keys and celebrate!
Your Home Search,
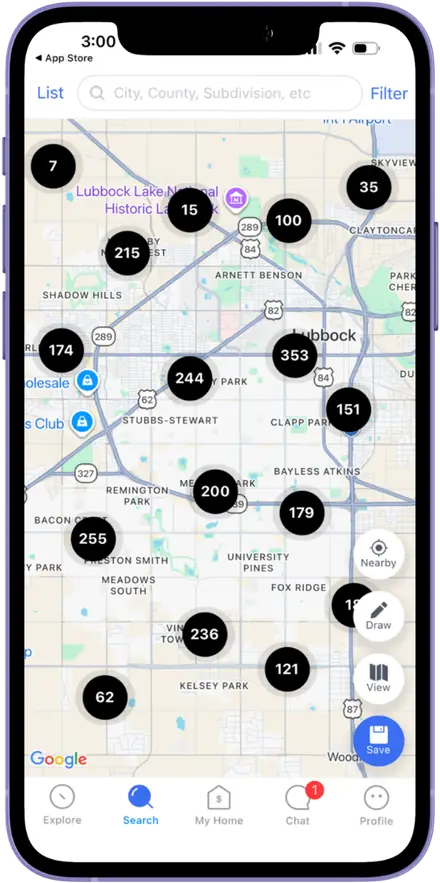
In Your Pocket
Download my free home search app to browse Lubbock listings, get notified the moment a home that fits your wish list hits the market, and reach me directly, all from your phone.
- Instant alerts when new listings match what you're looking for
- Save favorites and compare homes side by side
- Message me anytime with questions or to schedule a showing
Every Path Home Looks Different

Buying Your First Home?
No question is too basic. I'll walk you through every step, from budgeting and pre-approval to closing day, and help you find out whether you qualify for down payment assistance programs.
Meet My Lending Partners →
Moving to Lubbock?
Whether you're coming for Texas Tech, a new job, or family, I'll help you get to know the neighborhoods, schools, and commutes, with video tours if you can't be here in person.
Explore Lubbock →
Thinking of Buying New?
From spec homes that are move-in ready or under construction to building from the ground up with Lubbock's wonderful local builders, I'll help you every step of the way.
Browse New Construction →MORTGAGE CALCULATOR
Local Lending Partners
Getting pre-approved is the first step to buying with confidence. These local lenders are responsive, knowledgeable, and great to work with.


You're welcome to use any lender you choose.
Buyer Questions, Answered
How much do I need for a down payment on a home?
The amount you need for a down payment depends on the type of loan and your financial situation. While 20% is a common benchmark, many buyers put down less—some conventional loans allow as little as 3%, and FHA loans require just 3.5%. VA and USDA loans may require no down payment for eligible buyers.
What’s the difference between pre-qualification and pre-approval?
A pre-qualification is a quick estimate of what you may be able to borrow, based on information you share with a lender. A pre-approval goes a step further: the lender verifies your income, assets, and credit, then gives you a letter showing how much you’re approved to borrow. Sellers take offers backed by a pre-approval letter much more seriously.
How does my credit score affect my mortgage rate?
In general, the higher your credit score, the lower the interest rate a lender can offer. Your score can also affect which loan programs you qualify for and how much you pay for mortgage insurance. A lender can walk you through your options, and ways to strengthen your score, before you start shopping.
What are closing costs, and how much should I expect to pay?
Closing costs are the fees to finalize your loan and purchase, such as lender fees, the appraisal, title insurance, and prepaid taxes and insurance. They typically run about 2% to 5% of the loan amount. In some cases the seller can contribute toward them, which we can negotiate in your offer.
How long does the homebuying process usually take?
Every search is different, but many buyers find the right home within a few weeks to a few months. Once your offer is accepted, closing usually takes about 30 to 45 days while the lender, appraiser, inspector, and title company complete their work.
Can I buy a home if I’m self-employed or have irregular income?
Yes. Lenders will usually ask for more documentation, such as two years of tax returns, profit-and-loss statements, and bank statements, to confirm your income is steady. Talking with a lender early helps you know exactly what you’ll need.
What’s included in my monthly mortgage payment?
Most mortgage payments include principal and interest, plus property taxes and homeowners insurance, which are often collected in an escrow account. Depending on your loan, it may also include mortgage insurance. HOA dues, if the home has them, are usually paid separately.
What is a 2-1 buydown, and how does it work?
A 2-1 buydown temporarily lowers your interest rate: it’s 2% below your note rate in the first year and 1% below in the second year, then returns to the full rate from year three on. The savings are paid for upfront, giving you lower payments in the early years of your loan.
Who pays for the 2-1 buydown—the buyer, the seller, or the lender?
Any of them can. It’s often paid by the seller as a concession negotiated in your offer, and builders and lenders sometimes offer them too. Buyers can also pay for it themselves. We’ll look at whether it makes sense for your situation.